Double blow for double cab pickups
From 1 July 2024, double cab pickup trucks will be generally classed as cars for direct tax purposes. What will change and will you be affected if you already drive a company-provided vehicle meeting the description?
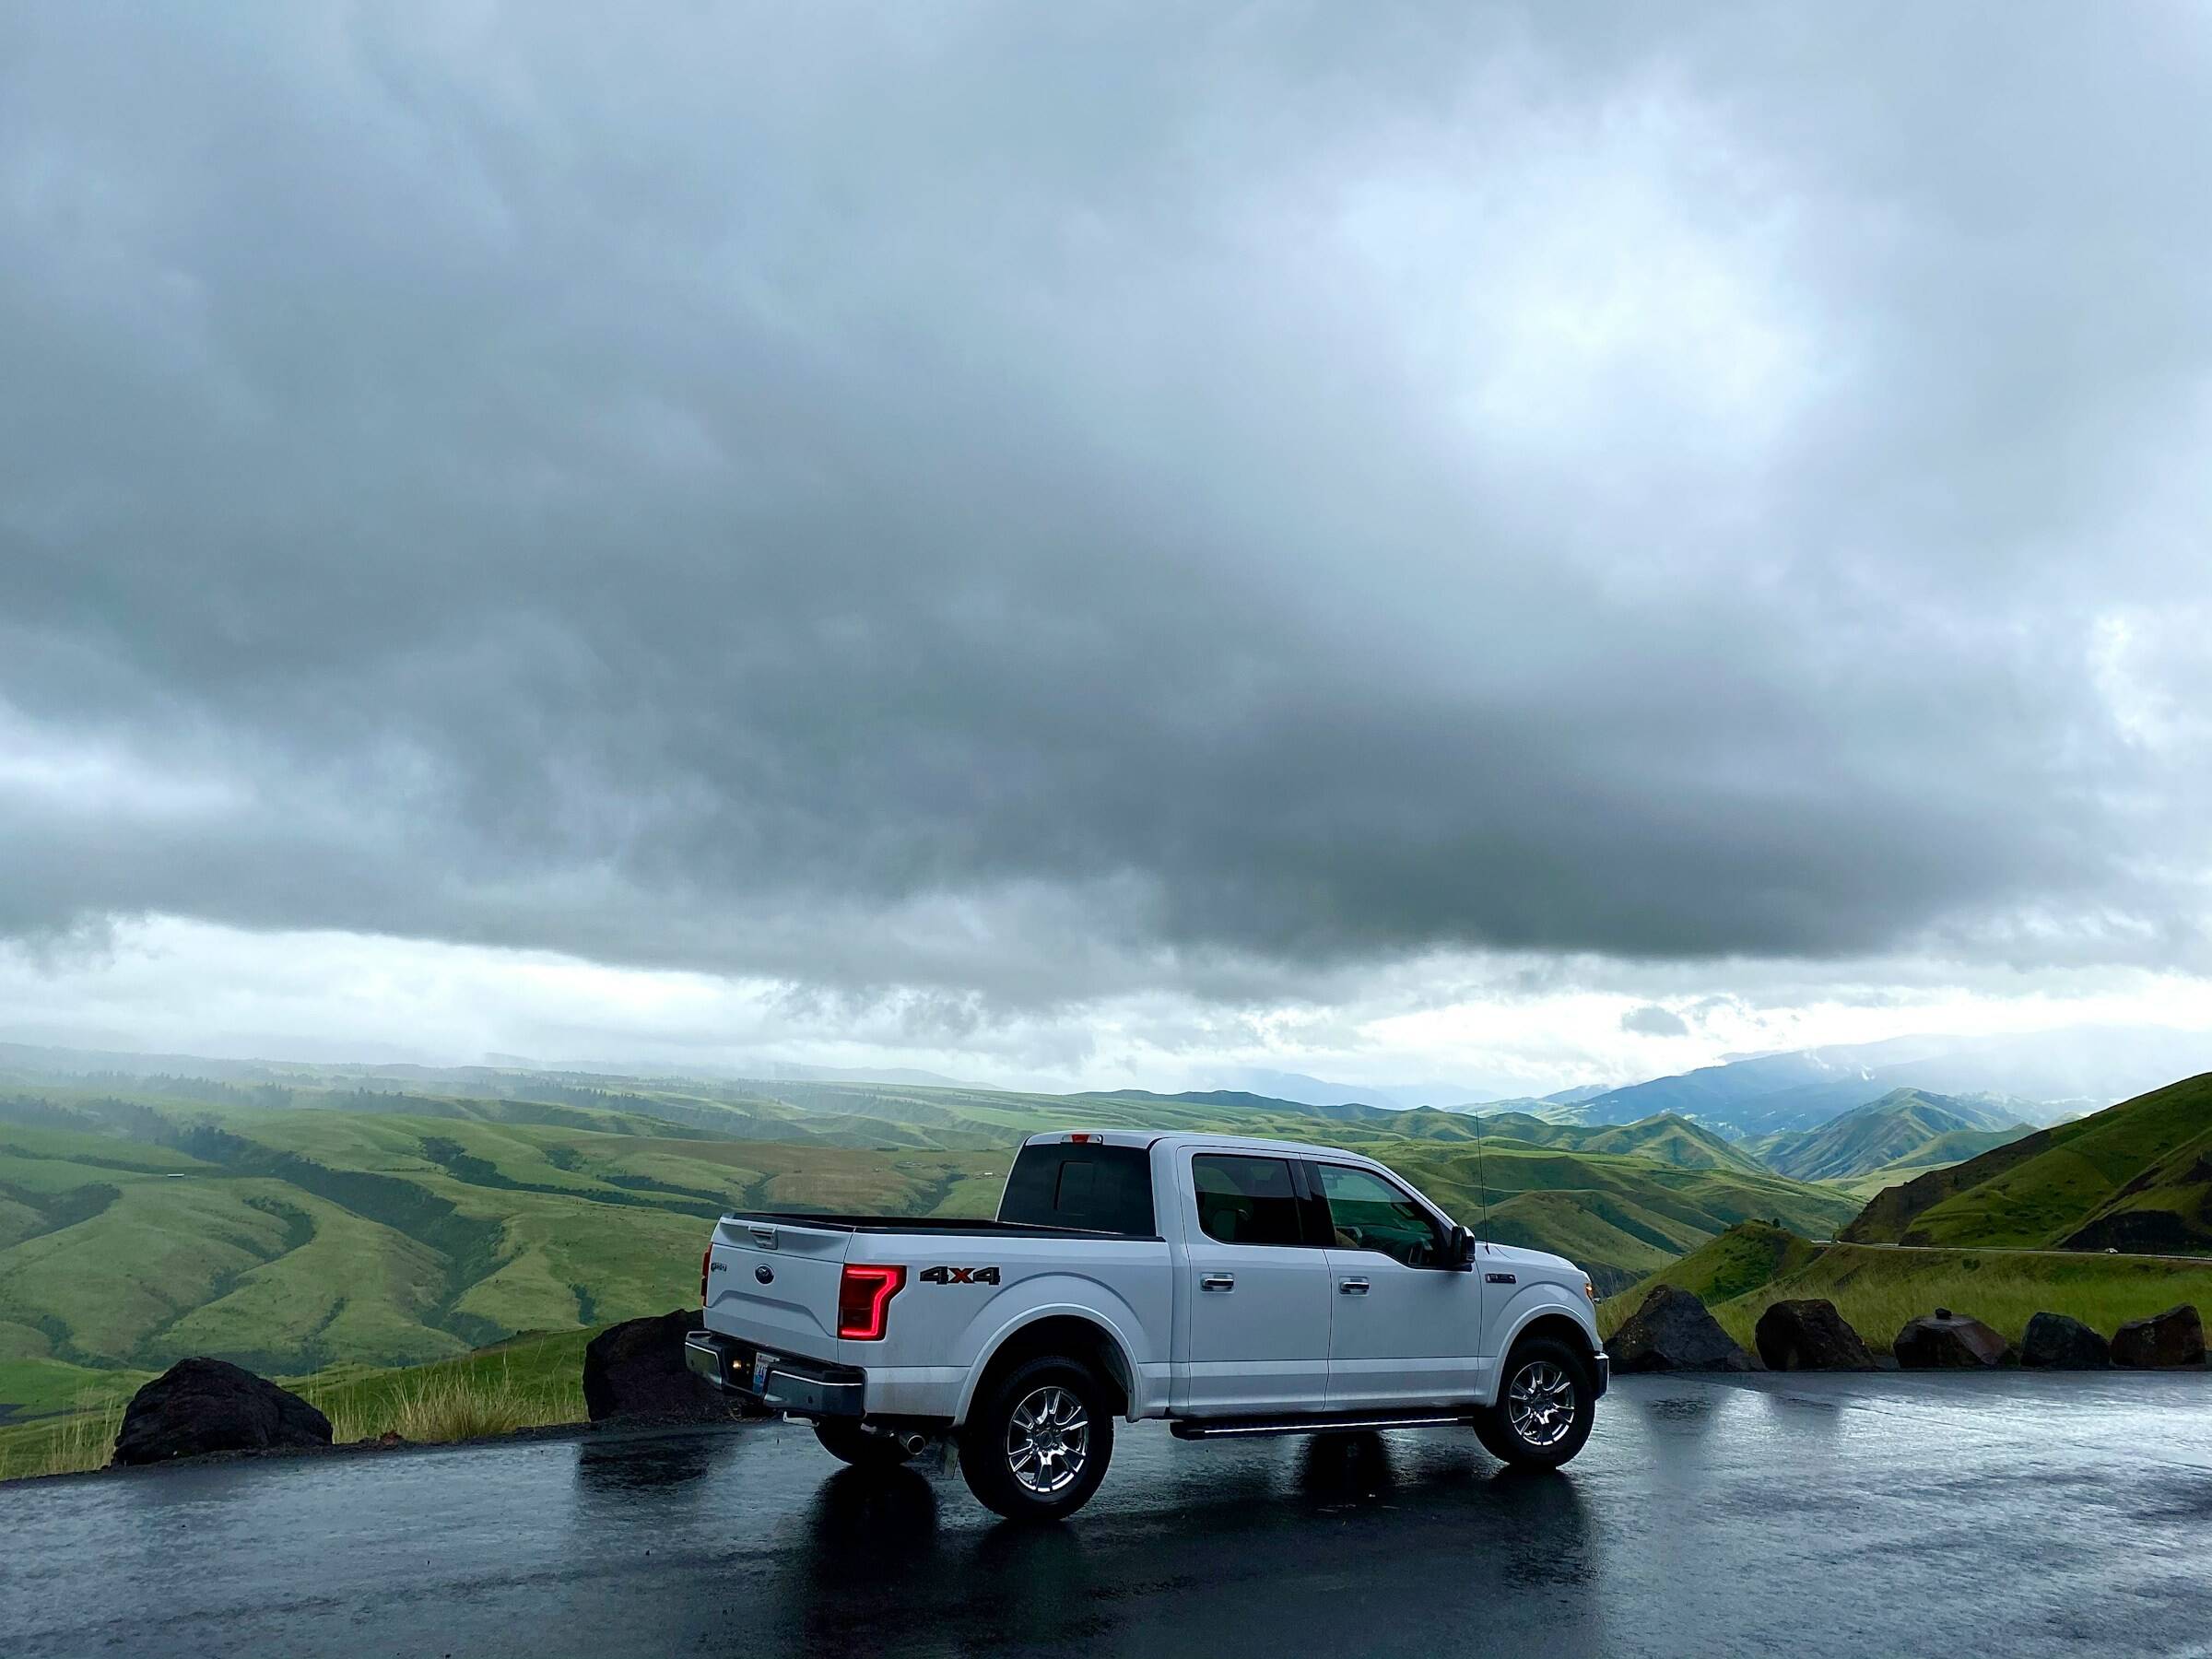
Company cars have become increasingly expensive for both employers and employees in recent years, unless employees opt for hybrid or wholly electric choices. However many have taken advantage of a perceived loophole to enjoy the more favourable tax treatment applying to company-owned vans. The “loophole” comes about because HMRC has previously applied the VAT definition of a “van”, which depends on the vehicle having at least a one tonne payload. However, a 2020 Court of Appeal involving Coca-Cola ruled that applying the VAT definition was not appropriate for income tax purposes, finding that this was too narrow a margin, e.g. two virtually identical vehicles with slightly different payloads could be classed differently.
Instead, the approach from 1 July 2024 will be to determine the status of a vehicle as a van or car by looking at the primary suitability at the time it is provided, i.e. is it primarily suited to convey goods? If so, it will be a van. However, as most double cab pickups are equally suited to carrying passengers they will be classed as cars.
There will be a transition period for vehicles already ordered, purchased, or leased before 1 July 2024, as detailed in HMRC’s employment income manual. Such vehicles will continue to be treated under the VAT rules (i.e. as a van) until the earlier of:
- disposal date
- lease expiry date; or
- 5 April 2028.
The change will also affect the employer’s position for capital allowance purposes. Vehicles classed as cars are subject to far more restrictive capital allowances. Cars generally don’t qualify for the annual investment allowance or full expensing. Again, there is a transition period, but this will only apply to expenditure incurred between 1 July 2024 and 31 December 2024 where the contract was entered into before 1 July 2024. Further information is available in the capital allowances manual.
Related Topics
-
Deadline to file paper self-assessment returns
-
Autumn Budget 2026 – what are the key tax announcements?
The Chancellor delivered the Autumn Budget on 28 October, announcing a mixture of tax increases, new reliefs and changes to the way tax is administered. Although the headline rates of income tax, National Insurance (NI) and VAT remain unchanged, there are some significant changes affecting business owners, landlords and private individuals. What are the main announcements?
-
Menopause and mental health support can be tax-free
Employers offering counselling and wellbeing services to staff have received clarification about which services can be provided tax-free. Updated guidance specifically includes menopause and mental health support, but not all employee assistance programmes will qualify. What should employers check?
 This website uses both its own and third-party cookies to analyze our services and navigation on our website in order to improve its contents (analytical purposes: measure visits and sources of web traffic). The legal basis is the consent of the user, except in the case of basic cookies, which are essential to navigate this website.